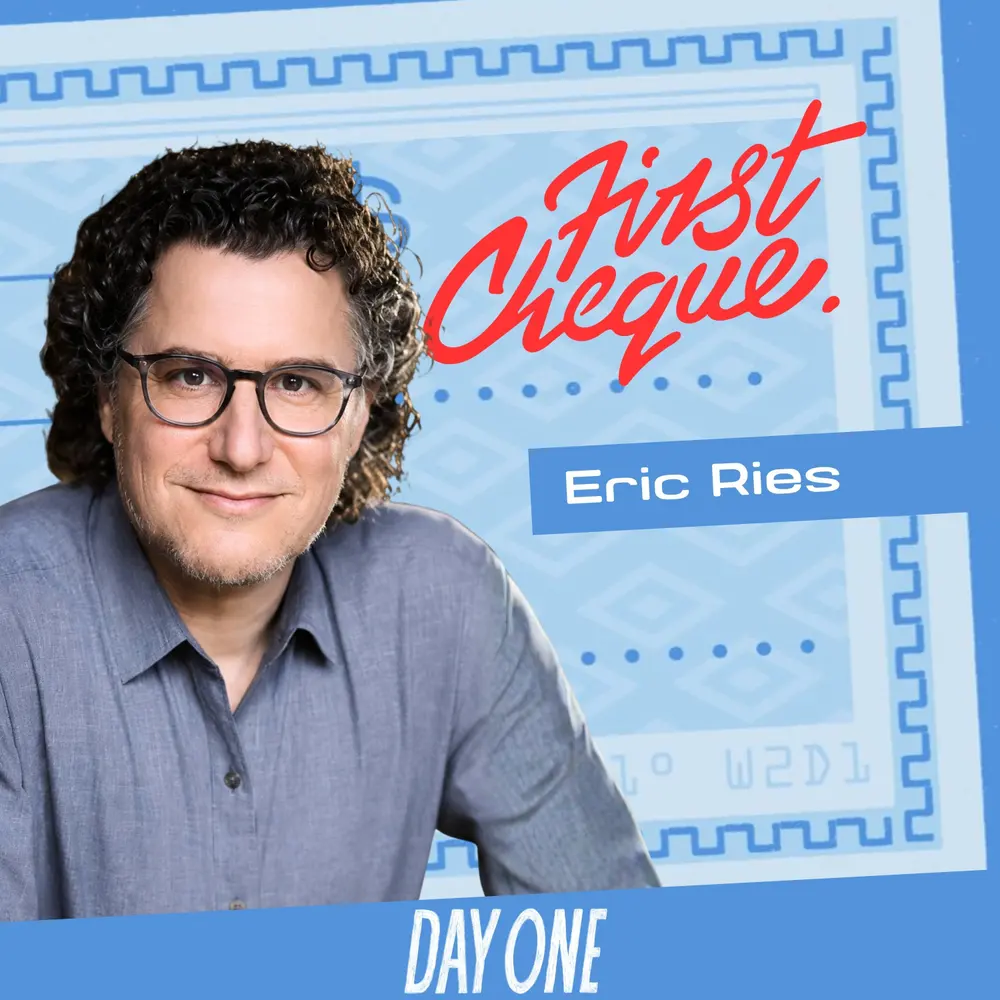
Eric Ries — author of The Lean Startup and The Startup Way, and founder of IMVU and the Long-Term Stock Exchange — joins Cheryl and Maxine to talk about his new book, Incorruptible, which examines why companies drift from their mission once investors and boards take over, and what founders and early investors can do to prevent it.
Eric unpacks what he calls “financial gravity”, the force that pulls companies toward extractive, value-destroying behaviour even when everyone believes they’re pursuing profit. He explains why many widely taught governance best practices are actually shareholder-value destroying, and why the earliest stage of a company is the easiest time to build in protections against this drift.
He breaks down the “spiritual holding company” structure, using Novo Nordisk’s century-old nonprofit foundation as an example of why mission-guardian structures make companies far more likely to survive long term, tells the story of a startup that took a million dollars from Purdue Pharma to push opioids and why it destroyed the company, and closes with the board meeting early in his career where he expected to be fired — and the lesson that “harder is easier” when you stand for something you believe in.
About the guest Eric Ries is the author of The Lean Startup and The Startup Way and the founder of IMVU and the Long-Term Stock Exchange. His latest book is Incorruptible.
About the show First Cheque is hosted by Cheryl Mack and Maxine Minter and produced by Day One®, trusted partners in the technology space and the team that helped build Blackbird Ventures’ Wild Hearts.
Chapters
0:00 Intro 4:10 Eric’s first investment: his own money into IMVU’s friends-and-family round 9:15 From Lean Startup to Incorruptible: one continuous project 17:40 The tortilla company, private equity and pricing power 21:30 Why so-called governance best practices are often value-destroying 25:50 Naming the problem: financial gravity 30:20 What founders and early investors can do at the earliest stage 36:45 The Olympic-athlete analogy: build protections in early 41:10 The spiritual holding company, via Novo Nordisk 48:30 Why “good governance” companies have underperformed since 2008 52:15 The Purdue Pharma story: how a million dollars destroyed a company 58:40 Biggest Brave Moment: a high-stakes board meeting Transcript Search or select a timestamp to jump ▾ 0:00 Eric Ries: We are rewarding and incentivizing this extractive behavior, often which comes at the— it's like fatal to the host organism, but the people that do the extraction make money from it. We call that profit today, but Adam Smith would've called it exploitation. Many of today's so-called best practices that we teach about how investors should behave on boards, about how companies should be operated, like the cultural leadership practices, and about how companies should be structured, the right relationships they should have between their employees, their customers, the company, and their investors. Many of these best practices are value destroying. If you just wanted to make money, like go be an investment banker or a corporate lawyer or something like so many, there's so many easier ways. Why, why on earth would you be in this ecosystem? 0:44 Speaker: There are other ways that are easier than backing early stage companies to make money. So many. 0:50 Speaker: Okay. 3, 2, 1. Hey, I'm Sheryl. I'm Maxine. This is First Check, part of Day One, the network dedicated to founders, operators, and investors. 1:00 Speaker: If you want to be a better early stage investor, this is the show for you. 1:02 Speaker: So TL;DR, If you don't want to suck at investing, listen up. 1:12 Speaker: I am so excited for this one. I am like true, true, true, true fangirl moment. Like first text I've ever read in the space was my gateway drug to venture building. And now we get to speak to him, to Eric Ries. I know. 1:30 Speaker: I cannot believe. And like So it's like, I just can't even believe we just, we like, like they reached out to us. They were like, hey, do you want an advanced copy of the book? And I was like, I have reached status of getting advanced copies of books. Like I have made it. And like the first book, you're right, same. Like I still quote things from The Lean Startup. It is the very first book that I think any entrepreneur or like VC starts to read when you join this space. You're like, what book should I read? Oh, The Lean Startup. I didn't even know there was a Red Book, by the way. I just know there's a Blue Book, and I love that he made them red and blue. Red pill, blue pill. Yeah, 2:08 Speaker: I love it. You can take the red pill, blue pill. Yeah, 2:11 Speaker: exactly. 2:12 Speaker: I mean, I don't know that you would look at the two. The red pill, by the way, is the startup way, but that is more for corporate innovators. 2:18 Speaker: Yeah. 2:19 Speaker: I guess there's a meta comment there of taking the blue pill is building yourself and taking the red pill is doing it in a larger organization. 2:27 Speaker: Yeah, that's— I, I got that from that, which is cool. But yeah, I am so excited to talk to Eric Ries. I just think he's the coolest person in the world, and I, I cannot wait to hear more about this new version of— I also, I'm, I'm so excited to hear how he went from, okay, like, let's build and pivot and grow and run fast and break things, to, hey, uh, there's a whole bunch of corruption in the world, which is, you know, something we're going to dive into with his new book. And so it'll be good to learn how he went from that to that over the last 15 years. 2:58 Speaker: Yeah, hear some of the scar tissue. But also, I mean, I think it's thematic, right? Like, I think there is— we're thinking about building things that last now, whereas back in— I think he wrote it in 2013, right? 2014. He wrote The Lean Startup in 2014. Yeah, it was, you know, build fast, break things. And now it's like, oh, actually, maybe we shouldn't break stuff. Maybe we should build for the long term. So I can't wait to get into it with him. 3:30 Speaker: Amazing. Let's welcome him on. 3:32 Ad: You're listening to a dayone.fm show. 3:39 Ad: Founders scale faster on Deal. Set up payroll for any country in minutes, hire anyone anywhere, get visas handled fast, and get back to building. Visit deal.com/dayone. That's d-e-l.com/dayone. 4:02 Speaker: If you're a founder or operator trying to scale, here's the reality. Australian hiring is getting harder, salaries are at record highs, and the talent you need is increasingly out of reach. The best operators are quietly building offshore teams of engineers, marketers, accountants, and analysts at a fraction of the cost. PearTree does it differently. 4:19 Speaker: They headhunt highly skilled talent from the Philippines and South Africa with full-time transparency on where every dollar goes, so your team is paid fairly and they are fully focused on your business. 4:29 Speaker: As a Day One listener, you'll receive a free team audit to identify where offshore talent could move the needle in your business, plus 20% off on your first hire. 4:37 Speaker: You can learn more at dayone.fm/peartree. That's dayone.fm/peartree. 4:49 Speaker: Let's jump into it with Eric. So Eric, the very first question we all always ask all of our guests is, and I'm so excited for your answer, uh, what is the very first thing that you ever invested in? 4:58 Eric Ries: Gosh. Um, well, it had to have been one of my own companies, I think. Um, I think when I did my first Silicon Valley startup, this would've been in 2004 maybe. I did, I did not have a lot of money to my name, but at the time. I scrounged up just a little bit so that I could be on the cap table myself. And that was definitely my first investment. And I didn't know anything about investing then. It seemed very arcane. So yeah, I've done it quite a few times since then. 5:31 Speaker: Do you remember what company that was? 5:32 Eric Ries: Yeah, that would have been IMVU, what I wrote about in The Lean Startup. Started that company in 2004. And although we mostly were angel-backed, we did a friends and family round. And I remember gathering some actual friends and family and getting them into the round. And I put some money in myself. It was really, it was very exciting. 5:49 Speaker: Yes. 5:49 Speaker: That's so cool. That's so cool. If you don't mind me asking, like, was that your first job that you had been working on or, and you just hadn't really invested before that? 5:57 Eric Ries: Um, that was definitely my, like, that was my first real, real job in Silicon Valley, like as a, as a founder. But I had, I had the people I founded the company with, we had all worked at a venture-backed company. Mm-hmm. That was like a dot-com era holdover, um, after I came outta Silicon Valley. And of course I had done a, a dorm room startup while I was still in college during the dot-com bubble. So, 6:18 Speaker: so cool. 6:19 Eric Ries: It definitely felt like that. It felt like, okay, now I have, I have arrived in Silicon Valley and I'm doing the thing that I came here to do. You know, it was very exciting to be, to be part of, uh, part of an, an opportunity like 6:31 Speaker: that. Writing your first check into a company. 6:33 Eric Ries: Yeah, yeah, yeah, exactly. 6:35 Speaker: Yeah. Just happens to be yours. 6:36 Eric Ries: Yeah. Yeah. Well, I didn't, I didn't want to be an investor and I still I don't really think of myself as an investor, although I've obviously, gosh, I wonder if I've made more money now as an investor than as a founder total. I'm not sure. I'm not sure actually. I'd have to actually add it up. It's kind of confusing those ways. But after IMVU was successful and especially after the success of Lean Startup, a lot of people asked me to get involved in their companies. And sometimes I would do it as an investor. Sometimes I would do it as an advisor. Sometimes I would do it as both. But I kind of like I kind of like being an advisor more than investor. Like I like being on the common side of the cap table versus the preferred side. So maybe I'm masochistic that way, but I really enjoy the sweat equity, um, kind of even more than the financial equity. Although of course our economic system is certainly geared for investors and the advantages that they receive. So I, I've enjoyed those as well. 7:25 Speaker: That totally tracks. And I think, I mean, you've hinted there a couple of times, but I mean, you wrote probably one of the most important books in the startup ecosystem. and the, actually, like the principles behind this kind of iterative way of building, or at least put pen to paper on that iterative way of building in a way that I think now has become kind of woven into the collective fabric of building and pivoting at the early stage. And then you have built and written 2 more books now, or soon to be 2 more books, which I'm really excited to get into and talk to you about your new book. But I'm really interested in the arc that, that has taken you on? Because if we think about building a company, then The Lean Startup as a gift to the ecosystem, right? Like how to be iterative and how to like move fast and break things. And it was very much of the zeitgeist at the time. And then The Startup Way, starting the long-term stock exchange, and then now Incorruptible. Can you maybe take us on that journey? Like what changed for you, at least from the outside, which looks like 2 very different ways of thinking about the world, right? Moving fast, breaking things, running really fast at things, and then thinking about, you know, now with Incorruptible, thinking about how do you create things to last? How do you create things that, you know, maintain their structure? 8:38 Eric Ries: Yeah. You know, from the outside, I know people perceive this as me doing a bunch of different things that all seem very different from each other. But from the inside, what you have to understand is to me, it's always been just one thing. And I don't really understand why it has played out the way that it has. You know, I don't, know how to make a master plan for these things. I, I tried to be discerning about, okay, what, what does the world need now? Okay, let's go do it. So to me, it wasn't really that different, you know, doing startups versus writing about startups, writing code versus writing prose. Like, I don't know, it's not that— my brain is not that different. And I didn't know— yeah, I think you have to understand, when you put something out into the world, you, you don't know what's going to happen. So I didn't know that Lean Startup would take over my life. I didn't know it would change the world. I, I hoped it would have some level of success, but obviously what has happened in these 15 years is far beyond my wildest expectations. And the question I just keep asking, like, I'm just very curious. I want to understand how things work and I want to put the things I learn into practice. So I felt like Lean Startup was a very comprehensive answer to a slice of this problem. You know, what is the manager? It was really a managerial book, a book about the management systems of of high uncertainty and to formalize a bunch of ideas that were floating around in the zeitgeist to maybe contribute a few original ideas to put it together into a package that allowed us as an ecosystem to talk about something we couldn't talk about before. If you look at the pre-Lean Startup discourse about topics like pivots or MVPs, it's very confusing. Like, it's actually really interesting to watch practitioners write and talk about that era before because it's not like we weren't pivoting before. It's obviously as old as entrepreneurship itself, but if you read biographies of famous entrepreneurs, if you, uh, would just read the self-accounts, the interviews of prominent entrepreneurs, it just, it was very confusing. We couldn't really reason about what was going on. And so I, I started to call this the development of conceptual vocabulary. Like it's not actually putting a word to a thing. The word is not what's important, but to identify the concept. that would allow us to argue about, debate it, spread it, oppose it, whatever. Even the people that hate Lean Startup and think it's stupid have to spread the meme in order to criticize it. That's how it works when you put your finger on something. 11:00 Speaker: All publicity is good publicity, that kind of thing? 11:03 Eric Ries: I guess so. I think of it more like we're trying to prove certain theorems, you know, and everyone contributes to the proof, even the people that are being skeptical or having opposition. And in fact, you see that in The Wisdom of Crowds, research that the effectiveness of a group, the average effectiveness of the group is increased even when you add someone who is ineffective to the group under a wide variety of circumstances. So it's like having someone who disagrees with everybody else, even if they're wrong, stimulates a lot of good thinking. So I'm actually, I've become, I've learned in my old age to be grateful to these critics because by their manifest incorrectness, they help people find the truth. You know, it's all good. 11:43 Speaker: What a great way of looking at that. 11:45 Eric Ries: Yeah. Well, you otherwise you go crazy because, you know, you put an idea into the world. You also get a lot of vitriol, um, and, and people who don't like it too. Um, although I guess it helps that I look the way that I do. I don't get as much social media hate as a lot of other people do. So I, I'm, I am grateful for that undeserved though it may be. In any event, so, so to me, the question was like, what is true? How do you make great companies? You know, what does it take? And I felt like Lean Startup was like the first attempt at a general theory. of entrepreneurship, right? Like just a very, very, very basic— to me it seemed like, like the, the beginning of something, not the end of it. And so I was very pleased that lots of other people— there's like a zillion Lean for X type books that were written on top of it. A lot of people built on that infrastructure. People have built and sold consulting companies out of it. Like a lot of, lot of good stuff came out of it. But to me, all that felt very incomplete. Um, I started to work on what happens after companies get larger, and I had a whole life that most entrepreneurial people don't know me at all for this, but But in the corporate innovation world, corporate transformation world, they know me more for The Startup Way even than for The Lean Startup, the red book, not the blue book. Because I really spent a lot of time trying to understand what does it mean to do these things at scale? How does it work when you get to larger scales? I got to work on every conceivable kind of company. You name industry, sector, size, age, I'd done it. Product categories, I've been all over the place. And that was really interesting. And I felt like it took a while. It took a really long time to work out the details. What is the right management system for this? How do we turn an individual entrepreneurial insight into a portfolio? Like a lot of like, I consider very basic questions about accounting, about budgeting, about team construction that I just couldn't get answers to. Like no one seemed to know the answer. So it was like, I felt like I was once again doing this thing. And so as a result of this, look, it's really fun. Okay. Get to be the Lean Startup guy. Okay. This is extremely fun because every day people reach out to me for advice about investing in, building, revitalizing companies. So I just get presented with an endless buffet of interesting intellectual challenges that are also economically valuable to the person asking, which for me, that's like, that's just wonderful. So stimulating. So great. But I've also, as a result of that, seen how bad it can get. I've seen the dark side of this business too. Companies where the investors have ejected the founder in a totally unfair way. I talked to a company today, I got called today, literally 2 hours ago, 3 hours ago, got a call from someone who is dealing with a board that is just catastrophically incompetent, who on their watch presided over the squandering of like tens of millions of dollars of venture capital, brought in this person who's calling me to fix the situation. They did turn it around, got the company to profitable. And they're like, thanks, but no thanks. You know, we don't really need you. We could, they have like, you don't have any leverage here. We, you don't have to be paid fairly for your work. Don't, we don't want you to have any equity. Like we, we could get somebody else just as good. It was like, you guys, like, this is, this is unbelievable. It was just such a, and I named the company that would be like, I can't tell you how many comments you would get from people who would be like gnashing their teeth because it's a beloved company with tons, with a great community. And it's just, they deserve so much better. And what's happening now? And what does the board want to do? They want to sell the company for parts. That's the, that's the best they can think of for what to do. This is having, after having already purged the invest— they've already purged the founders. So now they're on a next generation of leadership that they're eager to purge. It's just, it's just sad. And so to me, it's like, if we just want to make great companies, we have to stop this. We have to put an end to this behavior. It is a massive tax on the productivity of our economy. So to me, it's very natural to just be like, okay, first of all, how do we create these companies? And then how do we preserve, scale, and protect them? And I think, frankly, the way we are teaching entrepreneurship today and leadership and governance and board, like a wide variety of managerial subjects are being taught in a way that I think is frankly naive and is just leading lamb after lamb to the slaughter. I think it's, I'm frankly tired of it. And so, as with all my books, they come from my own personal pain grappling with this thing, this thing that we can't name. And so my goal is to give it a name and we can reason about it properly. 16:02 Speaker: Yeah, that's one of the things that we, we were like, we were talking before, we were like, what has happened to him in the last 15 years that like we've gone from this exciting like pivots and we can get started and run fast and like so much of our vocabulary in this space has come from that book to, okay, the world is totally greedy and we need to fix it. I'm like, how jaded are you over these last 15 years? But it sounds like you've seen a lot. 16:26 Eric Ries: As the kids say, I seen some things. Yeah. But it's not just me. Okay. It's not just me. Just look, just read the news. Like, look around. We're drowning in this phenomenon. And it's bizarre. The book's been out, I don't know, just a bit over a month as we're recording this. And people have started to send me their corruption stories. Like, people will be like, oh, hey, Eric would like this. So like my inbox, like, so, and I've worked on this book for— 16:51 Speaker: Now your inbox is just filled with like depressing corruption stories. 16:55 Eric Ries: You have no idea how many stories people have sent me. 16:57 Speaker: That doesn't sound fun. 16:59 Eric Ries: It's actually great. It's, it's great because it gives me like a steady stream of new examples to talk about as I've been on book tour and stuff like that, which is, which is really great. Now, I don't know how many of them will translate to an Australian audience. You guys will have to, you'll have to help me. 17:11 Speaker: Give us one. 17:12 Eric Ries: Give us one. Um, I'll think that through. No, I mean, there's just, there's just tons of these companies. Uh, the most recent one that somebody sent me, well, I mentioned the one I just did, that was just today. What though was one that somebody sent me this morning? Oh, oh, it was a tech company that like I thought was a great company. Like it's a company I know the founders really well. And someone sent me this long diatribe about how they've been there for 15 years and they're leaving. They've had it. The company's become totally, and they were like laying out the bill of indictments. Like, look at all these ways in which they've lost their way. They're stealing the company, the customer's data, using it for AI training illicitly. And then they got caught doing it. It was just like such a predictable list of things. The one before that was a tortilla company. 17:53 Speaker: Like taco tortillas? 17:55 Eric Ries: Like taco tortillas. Like physicals, like I got a lot of food examples. 17:59 Speaker: What? 18:01 Eric Ries: Incredible. People are so upset about these food companies. Gets acquired by a public company or private equity, I can't remember which one it was. And you go on the Reddit forums for the company and people are just hair on fire. The tortillas are disgusting now. Because this is, and if you, if you read up on modern finance theory, this is called pricing power. Like the reason you would want to take over a tortilla company is not because you think, ah, this is the future of food. No, because you realize that you have a captive audience and you could take cost out of this business and they'll still buy. 18:34 Speaker: Totally. 18:36 Eric Ries: And the people complaining on the forum are probably still buying. A lot of them buy it because they have celiac disease or whatever. And this company was like really well known for producing like whatever. I can't remember what the thing was, but like they were known for certain special attributes that made customers buy the product. It made them extremely loyal to this brand. They were so upset. But from the private equity perspective, this loyalty is an asset to be exploited, not to be nurtured. And so we're just seeing this over and over and over and over again. You know, um, Rory Sutherland, uh, if you know him, has a great rant about going to a restaurant where their private equity had taken over the restaurant and a friend had recommended they go eat there. The friend takes one bite of the food and is like, oh, I'm sorry. I'm sorry. I could taste that this restaurant's been taken over by private equity. I didn't know. I would never have recommended it. And people laugh at that story, but like, why is it funny? Like, surely sometimes with their vast financial resources, when a company gets taken over, we would celebrate because with those resources, the product got better. But we don't have any of them. No one sends me those stories. No one can even name any of those stories because that's not what happens. What happens is we are rewarding and incentivizing this extractive behavior, often which comes at the— it's like fatal to the host organism, but the people that do the extraction make money from it. We call that profit today, but Adam Smith would've called it exploitation. harvesting what others have created. And I just think we have to stop valorizing this. I think those of us who are builders by nature, and I mean anyone in the venture ecosystem should be in this category, certainly founders, but a lot of early-stage investors are this way too. Why did we get into this business? Like, this is not a rational business to be in. If you just wanted to make money, like, go be an investment banker or a corporate lawyer or something. Like, so many— there's so many easier ways. Why, why on earth would you be in this ecosystem? 20:36 Speaker: There are other ways that are easier than backing early-stage companies to make money. 20:40 Speaker: So many. You 20:41 Eric Ries: know, I don't know if anyone's compared it to winning the World Series of Poker or something lately, but like, it's not that high. Yet we do it anyway. Why? Because we were called to do it by some extra financial motivation. And it's different for all of us. Some people are in it for quality or the environment or for taking care of their employees or because they want a certain problem they want to see solved in the world. I've met so many entrepreneurs, so many investors, so many different motivations, but I rarely meet ones that are just like, Money by whatever means necessary. 21:08 Speaker: So then what happens at some point that falls apart? 21:10 Eric Ries: It falls apart. So what's crazy, and I know this, that people hear this and they're like, come on, that can't be right. Okay. So I recognize upfront that there's going to be skepticism for this. And I'm used to that. You know, most of the things I've written, people have not immediately thought were great. Um, so you have to just trust me on this one. Many of today's so-called best practices that we teach about how investors should behave on boards, about how companies should be operated, like the cultural leadership practices, and about how companies should be structured, the right relationships they should have between their employees, their customers, the company, and their investors. Many of these best practices are value destroying. There's actually a whole chart in the book, it's just called Best Practices Destroy Shareholder Value. And it's not my opinion. This is not my opinion. There's tons of academics who work on these things. and have studied it. There's like a vast mountain of research that most people in the ecosystem have never seen, never even heard of. And we are preaching these things as if it's some kind of, um, like brilliant innovation. We've like finally figured out the ideal corporate form. In the US, it would be like a venture-backed Delaware C corp where the investors call the shots even though they are minority owners. Now, that idea is called shareholder primacy. And it has slowly but surely taken over the world in the last 40 or so years. But it's not some ancient pillar of capitalism. It's a relatively new phenomenon. And we are teaching it like it, you know, if you oppose this, you don't, you're opposed to capitalism itself. You're like opposed to value creation. You don't understand. It's just like, it's wild to me how, how indoctrinated we are to it when the evidence to support it is extremely poor. So that's, that's one of the reasons. But the other reason is there's something a little bit more subtle. And this goes back to that question of like, can we name the thing that we see? So when this happens to your favorite brand, what do you call it? What is the name of that thing that occurred and why? 23:09 Speaker: Pee-ification. 23:10 Eric Ries: Yeah, right? Like Corey Doctorow literally calls it enshittification. He's got a whole book by that title and it's, you know, it's mostly about the tech industry, but the tortillas are not In the tech industry, like, let's go. The restaurant's not like— this is a pervasive problem. And what I realized in writing and researching this book is that although we have a hard time talking about this, our grandparents would not have had a hard time. They would've said, oh, you're describing corruption. Easy. And we don't— people hear that, they're like, that's not what corruption means anymore. In fact, I'm not clear that any conduct meets our modern standard of the word corruption. It has been narrowed so far, as you can find out by watching the news every day and watch, watch what people will defend that our grandparents would have seen as indefensible. They would have said if that happened, you should like retire from public life in shame, let alone be defended out there saying it's okay. Outrageous. So we've just gotten used to corruption as like a natural state of affairs. We accept it as part of our financial system. And it is a massive tax on our economy, in addition to its many malign social consequences. So I wanted to give a name to the force that causes this corruption. Why are companies being dragged down, pulled down into mediocrity or worse? I call it financial gravity. And once you see it, first of all, now that I've mentioned it to you and now that people listening to this, like you're going to start to see this all over the place. And that's why you're going to start emailing me your favorite corruption stories. Like people are like, I never noticed this before, but now that you pointed it out, It's everywhere. And you'll start to notice it in individual interactions, like companies that you interact with. You'll be like, oh, they're raising money, raising price, raising my price on me because they can. They're doing something that I now secretly hate them. I can't switch right now, but if a competitor ever showed up, I would switch in a heartbeat, you know? And those liabilities don't show up on the balance sheet. In fact, the people that cause those liabilities are routinely rewarded and promoted and lavished compensation upon without ever being held accountable for the downstream consequences of the wreckage that they caused to so many companies. 25:25 Speaker: So fascinating. I, when, I mean, there's like so many threads I wanna pull in there. I'm like, exercise your self-control. Yeah, I know. I guess the first, and I think the most interesting one for us is when we think about the kind of like earlier stage of businesses, because that's where we spend all of our time as investors and a lot of the folks that listen to this show. 25:45 Speaker: We usually first check in. 25:46 Speaker: Yeah. So when we think about that very early stage and you're kind of like iterating around, but you found something that like actually works, what is the antidote to some of these things that you've talked about, right? What would you find yourself advising companies to do at a very earlier stage so that when the founder is still in the business and they are still kind of pursuing that passion, Right. Are there any suggestions you make or pillars you suggest that they build to create more long-termism in these businesses? 26:18 Speaker: And not just the founders, the early investors like us that are putting those checks in too, that maybe don't feel like we can ask them. 26:23 Eric Ries: Absolutely. You have such, such an important role to play here. The number one question, I've been on tour now for more than a month talking about these ideas. The book has a complete blueprint. for exactly what to do at every stage to prevent this. This is the other thing that people find this so hard to believe. This is not some arcane mystery. We don't know how to solve this problem. We actually do. There's whole branches of research that have been working on this for decades. There are companies that are able to defy this force, and they're all name-brand companies that you'll know. So as you start to read the book, you'll be like, wait a minute, they're in the club? I didn't even know. So this is totally solvable. But the problem is the number one challenge. People ask me in talks, in lectures, all across, all over the world now, people, all they want to know from me is, but are investors okay with it? Will investors be okay? Can I still raise money? And it's like, guys, first of all, this is what investors live for. The mission-driven company. Remember missionaries versus mercenaries? Whatever happened to that? Like, what has happened? But what's going on is that so many investors, after they become board members especially, but some of them even while they're writing checks, have had these governance best practices drilled into them so hard that they're actually really difficult to work with. I can't tell you, I, I, I, there's a whole section in the book called like how to talk to your lawyer about these things. There's a whole section called how to talk to your investor about it. And then there's a whole section About how to deal with people who passive-aggressively object by just asking questions. And this is like, this is the worst. 28:07 Speaker: I can't believe that's a whole chapter. It requires a whole chapter to like deal with the passags on your board. 28:14 Speaker: It's a whole chapter 28:16 Speaker: specifically 28:17 Speaker: just passive-aggressive questions. 28:19 Eric Ries: It's unbelievable. And, and how did I, how did I write these sections? very easily because for the years I was working on this book, I've been advising many, many, many startups to do these techniques. And I just ask them every time someone gives you one of these objections, will you tell me what it was so I can write it? I kept a list. 28:35 Speaker: How long was this list? 28:37 Eric Ries: It was, it's not that long because everyone's very repetitive. Like they're all the same. Everyone's, it's like all these bold contrarians. 28:45 Speaker: Okay. Give us, give us a couple questions. 28:48 Eric Ries: They would all be like this. They'd be like, well, Aren't you worried that— I'm fine with it, but aren't you worried that other investors might not like it? 28:57 Speaker: No. 28:58 Eric Ries: What is the answer to this question? No, I'm not worried about it. I don't know. And someone would be like, all right, what am I going to tell my LPs? Tell them that this way of building companies is more profitable. So you're going to make a lot of money for them because that's your job. Like so many of them are non-substantive and yet founders shrink from hearing these kinds of things. People are like, it's not standard, it's not this, it's not that. And the most devastating ones are of this form. Listen, I hear that you wanna do this thing, makes sense, but since we are so aligned here in the early stage, where do you need this? It's redundant. Maybe later when you have actual issues, like let's just get product market fit and worry about this later. Okay. I can't tell you how many companies I have worked with that put it off and put it off and put it off. And then as I say in the book, it's always too early until it's too late. And I have actually sat in the room with like the CEO turning to the CFO and be like, hey, whatever. Remember that thing that Eric was talking about? The mission protective provisions. That's what they call it in the law. Did we ever do that thing? And the CFO's like, oh, you were serious about that? Like, yeah, I told you to do it last year. He's like, yeah, but you told me not to worry about it 'cause it was too early. Yeah, it was. But can we do it now? Oh no, now it's too late. What? You should have told— if you were serious about it, you should have told me. It's like, I did tell you. It's like, when was it the right time? There's no right time. It's never the right time because this is an ideology. It is not— it's not actually like people are not engaging in their own critical thinking about this. They're just parroting something that they've been told to do. And of course is in fact, again, you have to reckon with this, is very good for their careers. If you are someone who is known for being a advocate for shareholder primacy and its affiliated ideas, that will be a career accelerant in so many different jobs, especially in investment banking and corporate law, like so many jobs. 30:52 Speaker: If you're a founder or operator trying to scale, here's the reality. Australian hiring is getting harder. Salaries are at record highs, and the talent you need is increasingly out of reach. The best operators are quietly building offshore teams of engineers, marketers, accountants, and analysts at a fraction of the cost. 31:11 Speaker: PearTree does it differently. They headhunt highly skilled talent from the Philippines and South Africa with full transparency on where every dollar goes, so your team is paid fairly and they are fully focused on your business. 31:23 Speaker: As a Day One listener, you'll receive a free team audit to identify where offshore talent could move the needle in your business, plus 20% off on your first hire. 31:31 Speaker: You can learn more at dayone.fm/peartree. That's dayone.fm/peartree. 31:43 Eric Ries: T-R-E-E. So yeah, so what can we do at the early stage? The early stage is the most important time because so many of these things are incredibly easy to do at the beginning and so difficult later. Not that they're impossible. I give lots of examples of companies at many different stages adopting these practices so that no one— I don't want anyone to feel like, oh God, it's too late for me. But at the early stage is definitely the best time. And in particular, I use the analogy for people like like, imagine you meet an Olympic athlete, okay? And you're like, tell me all— oh, master Olympic athlete, tell me all your secrets. I want to be an Olympic athlete too. And they're like, okay, well, first step before you even train in swimming or badminton or whatever, first step is you gotta eat right and you gotta be in the gym pretty much every day, right? It's like, got it. So after I become an Olympic athlete, then I'm gonna eat right and go to the gym? Like, no. 32:32 Speaker: That's not what I said. 32:33 Speaker: Wrong answer. 32:34 Eric Ries: Nope. Do that ahead of time. Ah, I see. If I go to the gym one time, you guarantee me that I will be an Olympic athlete? 32:39 Speaker: I ate a salad last night. That works, right? 32:42 Eric Ries: Yeah. It's like, I ate, I ate really well one time. So does that count? Like, not really. I don't think you're really getting it. And the number of variations of this, like, okay, you're telling me that even if I eat right and go to the gym, there's a chance I still might not become an Olympic athlete. I guess it doesn't matter. There's no point in doing anything. Actually, I can eat all the Doritos I want cuz it's hopeless. It's just like, guys, every possible misunderstanding. It sounds hilarious. That was a big jump there. Yeah, it's hilarious when you think about it in sports, but when you translate those same concepts into corporate governance, it like, I hear this all the time. It's like, oh, I didn't do it on my first day. I guess it's too late. I guess I could never do it. Oh, I did one thing. Now I never have to. Now I'm invincible for life. It's like, this is a lifetime practice and the earlier you start, the easier everything 33:30 Speaker: I love it. And I think, I mean, my hope is that everyone will get this book and have a read of the kind of core principles. 33:36 Ad: You're listening to a dayone.fm show. 33:39 Speaker: So are there any that are particularly salacious, like you've noticed most commonly trigger the list of pass-ag questions, uh, or, you know, principles that you suggest? For example, you have this idea of a kind of spiritual holding company. 33:56 Eric Ries: Yeah. Yeah. That's certainly the most controversial. Yeah. 33:58 Speaker: A little bit. 34:00 Speaker: Yeah. Just anything with the word spiritual in it in the founder world feels totally— 34:04 Eric Ries: Yeah. I knew, I knew that it was gonna get people, but I, but I, but the point is, so, so first of all, it did not, I don't mean spiritual in the religious sense. I mean spiritual in the sense of the animating spirit of the thing itself. And a lot of the book, look, this book begins like a normal business book, but then my goal was to do something a little bit different. And without spoiling anything, like you can see how the form of the thing deviates from expectations as you, as you read through. And that was all very intentional, and including using this language, because one of the biggest problems, like the philosophical problem at the heart of this, is that we just don't understand what a company is. We birth these things and then we don't control them. We don't understand what they are, and so we don't take measures that are remotely adequate to get the results that we want. So So the book is concerned first with the operational side of things, like how do we build a management system that can bind the organism, the organization, to a set of values? How do we align the business model? How do we get the culture right so that even if no managers are present, employees know what to do? And then of course, these questions about board and investor stuff. The pinnacle of this recommendation is this thing, the spiritual holding company. Now, This sounds radical, and I just felt like there was no way. I tried to write a lot of drafts of the book where I tried to make it sound as normal as possible, but we're so conditioned to do things a very specific way that people find this just very hard to accept. But it's a very simple idea, actually, and there's tremendous evidence in support of it. So let's take Novo Nordisk, for example. That's one of the largest companies in the world. Um, very successful company, been going for more than 100 years with a, um, with the mission of scientific research at the center. And I tell a bunch of stories in the book about companies that are destroyed because investors decide, or the board decides kind of randomly to betray the company, to sell it, to reorient it, to fire the founder, whatever. We've seen so many versions of that. People have tried to do that to Novo Nordisk, but it doesn't work. 36:09 Speaker: They had to lose it to the insulin, right? 36:11 Eric Ries: Yeah, yeah, yeah. So they, they, um, if you, if you, the story is really fascinating. The, the founders were a Nobel laureate and his wife, Augustin Marie Crowe, in the 1920s. Marie was a doctor herself, one of the first, um, credentialed doctors in Denmark where they lived. She got diabetes herself at a time when that was a fatal diagnosis. Like she was going to die from diabetes. And August asked her, in spite of this, would she still nonetheless come with him to North America to do a lecture tour? 'Cause he had just won the Nobel Prize. So they're in North America going and having these dinners with scientists. You know, he's giving these lectures. And at dinner one night, one of the, the person sitting next to her at the table, so the story goes, tells Marie that these, um, Canadian scientists have isolated insulin for the first time, a potential cure for diabetes. So she convinces August that they should extend their trip to North America and go see this scientific breakthrough for themselves. So they travel to Canada, they do sit down with the scientists, they, they put it through its paces, realize what this could mean. But their ambition is not just to cure Marie of diabetes. They're like, we have to bring this technology back to Denmark. So they make a deal with the Canadians. Can we license this technology from you and start producing insulin? 37:24 Speaker: With all of the Canadians, not just the Canadian scientists, just like— 37:27 Eric Ries: Yeah. Well, with the Canadian scientists. Yeah. No, no, it was with the scientists who, who were, who had the original breakthrough. 37:32 Speaker: There's only like 5 of us up there anyway. So. 37:35 Eric Ries: I mean, you know, it's, uh, I don't know what the population was in 1920, but yeah. That's a fair point. And what's funny about this is they, from the very beginning, both the Danish and the Canadian scientists, both, everyone's worried about a very specific future situation. They said, okay, imagine, like Cheryl, imagine you create, you had a life-saving drug that I needed to live. Okay, so I'm just like, I have to get this, I have to get a dose from Cheryl periodically or I would die. I would very much want you to make a fair profit. Charge me money for this. I want you to make money by selling me this thing, cuz I want you to stay in business. I want you to have every incentive to give me this medicine. Right. That makes sense. 38:14 Speaker: Yeah. 38:14 Eric Ries: But I would also live in fear. What if one day you wake up and say, wait a second, why do I have to charge Erica? 38:21 Speaker: You're gonna die without this. Why am I charging you a fair price? 38:25 Eric Ries: Yeah. Why do I have to charge you a fair price? I could charge you anything you want. I was like, bring me everything you own. 38:32 Speaker: I mean, really, what's fair? Your life? Like, how much is your life worth? 38:36 Eric Ries: What's— why life? How much is your life? How much is a human life worth is, of course, the core question that all these formulas have to grapple with. So anyway, like, that we— this is, to them, this was like a dystopian science fictional future that they were worried about. We actually, of course, live in this reality. 38:54 Speaker: And then Martin comes along and is like, hey. 38:56 Eric Ries: Yeah. Martin Shkreli is like, hey, we've actually had people do this. So this is not some like abstract concern. Anyway, they were like, look, in order to prevent that, the right way to build the Novo Nordisk Corporation— they called it the Nordisk Insulin Laboratorium— is to have a nonprofit foundation oversee or serve as what I call the mission guardian of the for-profit subsidiary. A 2-entity checks and balances system. And they set it up that way in the 1920s, and it has endured all this time. I tell a story in the book about a time where this, the trustees of the nonprofit had to intervene to protect the company in a transaction in which they created more than $500 billion of shareholder value. Novo Nordisk is a publicly traded company. It trades a zillion shares on NYSE every day. It is subject to all the same forces that everybody says would make them inevitably corrupt, and yet it endures. So this structure of having an entity that oversees another. I call it the spiritual holding company, and I had to invent a term for it because, believe it or not, there isn't one in the literature. 40:04 Speaker: About Novo Nordisk? 40:05 Eric Ries: Well, there— Novo Nordisk has one. That one is called the Industrial Foundation. 40:10 Speaker: Okay, 40:10 Eric Ries: that's a nonprofit that oversees a for-profit. But there's also companies that have what's called a perpetual purpose trust that performs this same function, like Patagonia is one famous example. You have companies that have an employee ownership trust that does the overseeing, like John Lewis Partnership in the UK. You have companies that are actually an employee cooperative or a network of employee cooperatives like Mondragón in Spain. I could do this all day. There's like the ESOP structure. There's the B Corp. You have the Ben& Jerry's model. You have the ESOP model like Taylor Guitars. There's— 40:45 Speaker: You also have the Anthropic model, which I think is one that as they continue to steam ahead, will create a real beacon for this way of governance, right? A real beacon, especially as we watch this real-time play out in ethics in AI between OpenAI that doesn't have, or doesn't have anymore, that structure, and Anthropic. 41:07 Eric Ries: Anthropic is in chapter 11 of the book. It's in the spiritual holding company chapter because I played only a bit part in the story. don't give me too much credit. But when I wrote the book, especially the early drafts, Anthropic was not that well known of a company. So it's actually been really wild to see how many times since the book— the delay between when the book was written and when it was actually printed, you know, there's like a delay before it comes out. The number of times Anthropic structure has been tested in that time has been remarkable. And I was like, oh no, how's it going to hold up? You know, we'll see. Well, so far so good. 41:38 Speaker: You might need to do a, uh, like re-release. 41:41 Eric Ries: I was like, am I gonna have to do an emergency revision to whatever? No, so far So far so good. Now, of course, it's still early days. We'll, we'll have to see. But anyway, there's so many variations of this structure that we didn't have a term for it. And this structure is old. It's not some newfangled thing. The German optics company Zeiss that makes most of the lenses in the world, they had this structure in 1887. So here's the incredible part about it. Companies that have this structure, like take the industrial foundation flavor for a second, because that's been the best studied. These companies are 5 times more likely to live to year 50 compared to conventional structures. They have far better financial performance. They invest countercyclically. They invest more in R&D. They take better care of their employees. There's like a zillion things that they do better. Now, I'm not here to say that therefore categorically everybody who has the structure will automatically do better. That's not the point. The reason this is so important is because, is not because of what it proves, but what it disproves. So the first time I ever met a company that had this structure, I was just doing a Lean Startup workshop for them. I was there with their CEO and their top executives, and we were doing this workshop, and I was just asking them some questions about the company, just chit-chatting. And I asked them about this ownership structure and how does it work? And they were explaining to me the foundations, all the stuff. And I was like, oh, I'm so sorry. That must be terrible. And they're like, what are you talking about? I was like, oh, you're owned by a nonprofit. You must not be able to follow all the best practices. And they're like, like what? It's like, well, you must not be globally competitive. You probably can't raise money in capital markets. You're probably dealing with a lot of virtue signaling BS from this nonprofit who doesn't understand your business. And I'm just rattling off all the things. That our modern finance theory— 43:34 Speaker: Look how far you've come. Oh, 43:35 Eric Ries: I've come a long way. 43:36 Speaker: It's like you just like read the list of past AG questions. 43:39 Eric Ries: Yeah, I, I had, I know them so well because I had them too. I was like, this can't be right. I was like, wait, this has been going on this whole time and no one ever told me? Because if you talk to people, like if you suggest to someone that they should adopt this structure and they ask their lawyer, they ask their banker, they ask their investors, even at the early stage, they'll be like, no, no, no, no, no. This can't possibly work because our modern finance theory predicts that these companies would not be globally competitive because they would not have the ruthlessness necessary to compete in our capital market. And that's not true. So therefore the finance theory is wrong. That's why these important— that's why these examples are so important. We have an inevitable rule, but if it was inevitable, there would be no exceptions. Yet there are these exceptions. So when founders talk to me about this, and this is so important, I really want all of your listeners who are investors to think about this. Founders come to me and we have this meeting. I've done this, I can't tell you how many hundreds of times now where I'm like, look, are you aware of the vulnerability you have to be ejected, to be ousted, to be this, to be that? We talk about all this stuff. We talk about dual-class shares. We talk about all the possible mechanisms. But then I mentioned this this structure to them, they're always like, well, that sounds really strange and weird. It's like, I know, but just because it's new to you doesn't make it new. And especially for founders that have already raised some money or that, you know, are having some success, they're often like, how come— if this is so powerful, how come I've never heard of it? It's like, right, that's not a question for me. You need to ask yourself this question. And for everybody listening, why did you have to learn about this from me? Why didn't you learn about it in business school? Why didn't your lawyer mention it to you as one of the options? Every time you write a term sheet into a company, why isn't your lawyer mentioning, hey, you know, you'd make more money if you wrote some of these provisions in the term sheet? How come it never comes up? How come when companies do talk to their lawyers, they're like, I don't know, investors might not like it? Well, where are the investors? Why are the investors standing up to be counted to say, actually, we would like to make more money, thank you very much? 45:46 Speaker: I would like to make more money if anyone asks. 45:50 Eric Ries: Right? It's a very straightforward thing. And, and yet, and yet, and yet this information is like an open secret hidden in plain sight. You know, IKEA, Costco, Patagonia, Vanguard, Aria. There's so many of these companies. I wish I knew the Australian examples. You'll have to teach me. There probably are plenty that just every day are doing their regular thing. Completely ignoring all these best practices. If they're public companies, they often get the worst possible scores from governance ratings agencies. One of my favorite funny factoids in the book is that since 2008, companies that have been rated to have good governance have underperformed companies that have been rated to have bad governance. 46:32 Speaker: Really? 46:33 Eric Ries: Yeah, it's crazy. Who is it for if it's not producing returns for investors? What makes it good? This has become a self-perpetuating ideology, completely divorced from the data, completely divorced from the reality of employees, customers, investors, like actual lived experience. And of course, completely antithetical to the intuition, what I call the builder's intuition that so many of us share, that the way to make a profit is to create more value than you capture. That's why we got into this business in the first And we are living at a time now when for-profit companies themselves are under attack from a new generation, especially who've lived only through an era of institutional collapse. And they only know for-profits as these evil caricatures. I don't blame the critics. That's what they've lived through. But if we want to maintain this system, we have to make a change or it's going to collapse. 47:28 Speaker: I think that's so powerfully said. 47:30 Speaker: Here's my question though. In practical terms, right? I'm thinking about, okay, well, you know, Anthropic have this spiritual holding co of AI experts that can oversee things, and that is a very, very important mission. But like, let's say your average SaaS company that I invest in, you know, they maybe make some HR software. Like, I'm just thinking in practical terms, we're gonna ask, they're gonna talk to this founder about creating a spiritual holding company to have an expert uh, talk about or like manage how they like ethically do, uh, HR charts? Like, I have follow-up questions on like the practicality of this for your average SaaS company. 48:11 Eric Ries: Totally. And, and I prom— you made me start with the most abstract and the most difficult concept, 'cause that's what you asked me about. But I promise the book, the book builds up to that through like a bunch of simpler things. to do. So like, let's, let's talk about, um, I don't know where, where would be a good place to begin, but like, since you mentioned the HR stuff, like, there's some really basic things that I think most founders view as kind of obvious, like too obvious to have to say out loud, but they're actually really important. So for example, there was a medical record startup here in the US a couple years ago that got caught up in the opioid scandal, you know, with the, um, And with these— the reason we have all these great stories in the book of scandals is because when the scandal breaks, eventually there's usually litigation. And then through the litigation, we have the internal records and documents. So when I say that this is— I don't have to be like, they were alleged to have done— no, the documents all came out. We know what they did. So here's what happened. So they were a venture-backed company. They had a huge valuation in the hundreds of millions of dollars, I think. High-flying, doing great. And Purdue Pharma came to them and offered them $1 million if they would push opioids basically on their doctors as part of the electronic health record, something, you know, basically advertising opioids to doctors, make sure you prescribe them to your patients kind of thing. And they took the money, they did the deed, and later this caused the complete destruction of their whole company. So go back to the meeting, okay? Like, imagine, because the critical thing to understand about so many of the destructions in this book is they're carried out in the name of profit. In the name of profit, we do something profoundly unprofitable. The person who got pitched by Purdue Pharma said, listen, I will give you $1 million. Think about how small that number is. It's not really that much money. Right. Would you risk your whole multi-hundred million dollar enterprise? I bet the founders didn't even know. It probably wasn't even a tier 1 decision made by any important person. It probably was just, Someone who thought their job was to make money for the company. Simple. We're being offered money, and I bet they probably had a meeting. What is the ROI of doing this? Well, we get the million dollars. What is the cost of doing it? Probably nothing. It will harm our trustworthiness in the long run. I bet there was someone in the meeting who was like, guys, guys, this isn't right. And everyone's like, oh, it isn't right. You know, like, where's your ROI spreadsheet, Mr. It Isn't Right? Right? Like, you know, you've been in those meetings. You know what I'm talking about? This is very, very, very common. Part of like— So part of this is just having an operating rigor to say, no, we actually are going to build an organization that stands for something in particular. I call them the fiduciary commitments of the company. Who would you rather die than betray? Anybody? Most founders, the answer is very obvious. They're like, well, yeah, my employees. Yeah, my customers. Yeah, the environment. Yeah, this, like, they usually have a pretty long list, but our formal legal governance theory, shareholder primacy, says that companies owe a fiduciary duty only to their shareholders. So this gap between the stated mission of the company and its actual legal purpose is what creates massive friction. and eventually destruction. So the simple stuff is like, can you actually just say out loud, what does the company stand for? What are the principles by which it operates? And then there's a bunch of managerial and cultural practices you can use to defend them. 51:43 Speaker: Which I think, I mean, it's an oversimplification, but I think something to call out, which is effectively we're talking about the kind of indoctrination of long-term thinking in a business, right? We are causing you to think long-term, to make longer-term decisions as, you know, long-term stock exchange. The principle continues, which is you, like, if you are making those decisions from a place of what is in the best interest of that mission in the long term, then you're going to make a longer-term decision. You're not going to take a million dollars from Purdue. You're going to protect trustworthiness because Matters in the long term. 52:22 Eric Ries: Yeah. Yeah. It's a very, it's actually a very simple idea. It's not like some radical, crazy thing. It's just like, let's just live up to our stated actual values. So, we do what we say we are doing all the time. 52:33 Speaker: And incredibly hard, right? And I think so wonderful for you, actually very similar to The Lean Startup, you're putting a kind of practical guide and a structure around something that kind of endures Long-term. 52:47 Speaker: And hopefully becomes part of our lexicon over the next 15 years. Like, now I stop quoting Lean Startup, I'll start quoting Incorruptible. 52:54 Eric Ries: I certainly hope so. 52:55 Speaker: That will be my hope. I hope everyone who listens to this goes and gets the book and has a read because I think it's going to become infrastructure for our industry, or at least I very much hope it does. 53:05 Eric Ries: Oh, thank you for saying so. I appreciate that. 53:07 Speaker: With our last question that we have, our last opportunity to ask you a good question, Um, I'm interested, given everything that you've done and all the books you've put out there and all the thinking and all the guidance, what is the bravest thing that you've ever done? What is your biggest big kahunas moment? 53:22 Eric Ries: Yeah. Yeah. Well, gosh, I don't know. It's hard. It's hard to say because I feel like this kind of career involves a lot of death-defying leaps where you just have to put one foot in front of the other and you don't know what it's going to be. Um, certainly people have told me as I've been traveling around talking about the book, how brave they find the book. Which I'm not sure what to make of that. Is that a compliment or is that— Is 53:44 Speaker: that a good or a bad thing? 53:44 Speaker: Yeah. Is it kind of passive-aggressively? Like, that's brave. 53:49 Eric Ries: Are people like, oh, that was very brave of you to throw your career away on this crazy, on this quixotic quest? But I'm used to that. So, so I don't mind that. I think, you know, building LTSC probably is the thing in this category because it was such, such an unlikely thing to succeed. Um, but it didn't It didn't actually take that much courage, like emotionally speaking. Like I got myself into lots of very dicey situations and I wrote about some of them, but mostly that was just putting one foot in front of the other. If I think about like what comes to mind actually for me is when, when I was very early in my career as an entrepreneur, I wasn't courageous because I thought everything was going to work out. So it's like, um, you know, when they teach gymnastics, One of the problems is that at a certain age, you're not afraid of falling off the apparatus. So you just, you fearlessly do the things. And then when you get to a certain age, you eventually start to realize that you can fall. And the fear of falling is actually like the major impediment to being able to do the sport. I feel like it was kind of like that. Like I had this, I got to a level of my career where I had something to lose. And all of a sudden I realized not everything's going to work out. And I can actually remember a very specific moment when I thought I was going to be fired. So this is before Lean Startup, before any of this stuff. I was an advocate for these ideas. We didn't even know what to call them. And they were seen by people as completely unworkable, crazy stuff. You know, it was not popular. It was not something that our VCs or, you know, any of the people around liked it. They liked the results that it got, but they, like so many people, were like, can we please have the results without the method? 55:24 Speaker: Yeah, because that's a thing. 55:27 Eric Ries: No, but they— because that's the best. They're like, can't we just follow the best practices? And I was incredibly stubborn. And, and in the early days, I didn't mind being stubborn. I'm like, no, no, no, this is the better way. And I would, you know, fight with them about it. But as the stakes got higher, I started to realize that I work for them. Anyway, I was— I can really remember preparing for a meeting where I was sure I would be fired because they were like, look, we have to have a meeting. We're having a board meeting about this. We can't keep doing— can't keep going on this wacky different way. We need you to just grow up and be more professional and like do things the conventional way. That's what we need. Somebody— as soon as people start saying things like this, they say, we need somebody in your seat who can do this thing. And when they start saying stuff like that, they're starting to separate you from the seat, right? Like now we're starting to recognize that you are not indispensable here. You can be removed. And I had never been through that before. I'd never even been fired from a job. Ever. I never even had a low performance rating. I never failed a test. Never. So I'd never had anything like that happen to me. And I had this moment of like, what they were expecting— in retrospect, it was so silly. They were just expecting, look, if I just come to the meeting and pay lip service to what they want to hear, probably that would have been the end of it. To them, it wasn't a big deal. They were just bringing me to heel, as they do with lots of people. And I was like, am I going to do that? Am I going to come into this meeting and say, yes, sir, we'll do it your way? For sure. And I just, I was like, I, I can't do it. I just can't do it. 56:54 Speaker: So did you get fired? 56:55 Eric Ries: So I didn't get fired in the end. That's what's so funny about it is I thought for sure I was gonna get fired. And then I, I just went to the meeting. I was like, look, bottom line, what you're suggesting is not gonna work. And what I sim— suggest, like the thing I'm doing, this is what's working for us. So you can fire me if you want, but you can't get me to do something that I don't believe in. And I think it turned out that their threat to fire me had been a total bluff. I was like keeping that company running with my bare hands. Like, I look back at it now, what were they gonna do? Were they gonna get to come clean up this mess from, even from their point of view, thinking it was a giant mess? What were they gonna do? You know, anyway, but, but also the CEO and some of the investors were very loyal to me. So, so it would've been a, it would've been a big, you know, company stopping moment. We'd have to have this big civil war fight and they were just like, eh. These best practices are great. We don't feel that strongly. You know, it was, it was true. But anyway, but so, so it turned out to be a big nothing. But in, for me, it was a very seminal moment because I had this moment. I realized, wait a second, if I go in there and capitulate, then that's what I'll be remembered for. They're not gonna remember me as the wise person who follows these best practices. They're gonna remind me it was the guy who folded in the face of this pressure. Conversely, if I go in there and, and actually tell them what I believe, first of all, they're gonna find out what I believe. A lot of the fights we were having They didn't have any idea why we were doing what we were doing. So I was like, this will be my chance. Like, I'll be a defendant on the stand and I will give my speech. I will tell them why I'm doing the things that I'm doing, but also they will know what I stand for. And I bet someday in the future they'll be in a situation where like, you know what we really need for this company? We gotta find someone who's like irrationally committed to going faster. This company's just too slow. Do we know anybody like that? What 58:40 Speaker: about that one guy that like totally 58:43 Eric Ries: Remember that guy we fired for going too fast? Let's get him. He could do like, he wasn't good for that company, but I was like, I'm gonna stand for something specific and you never know what might come. Something good might come from that. And I just feel like that has served me so incredibly well in the years since, which is just like, just, I can't be somebody else anyway. So let me like actually come in and say what I think. And try to make the best case I can for it, and then let the chips fall where they may. And I just— now I've come to recognize that in so many of the leaders that I admire, that they're just really who they are. They don't try to be somebody else. They're not putting on a performance or a show, and they're willing to do the extra work that their own principles require. So if you tell them— a lot of the issue with mission-driven companies especially is, and I remember this, this is the fight I was having with them. They're like, isn't it more work? To do all this extra stuff that your principles demand. And it's like we've entered this age where like being lazy is a virtue. So it's like if something's harder, like everyone's like, oh, it's like a criticism. And the people I admire the most, people like, yeah, it is harder. 59:51 Speaker: It's more work. But also like we're doing so much work for this anyway. So like— 59:56 Eric Ries: Right, exactly. Why would we compromise this? This is absurd. I call a principle in the book harder is easier. You actually make your life so much easier down the road by standing for something. And that has definitely been my experience. 60:07 Speaker: I'm in love with that. 60:08 Speaker: I love that. So powerful. I can't wait to be quoting this book for the next 15 years, which is how long I have been quoting The Lean Startup. 60:16 Eric Ries: Oh, thank you. Thank you. 60:17 Speaker: Harder is easier. That's already in my lexicon. Harder is easier. 60:20 Speaker: It's in, it's downloaded in. Thank you so much for joining us, Eric. This was amazing. 60:24 Eric Ries: Oh, totally my pleasure. 60:26 Speaker: Thank you, Eric. No transcript lines match that phrase. Try fewer words.
 ▶
 ▶
 ▶